Retirement protection guidance across Southern CaliforniaCall 951-858-4085
Retirement protection & annuity strategy

Turn part of your savings into more certainty.

Explore ways to protect principal, create predictable income, and reduce the impact of market losses—without treating every retirement dollar the same.

Educational, no-pressure guidance. Annuities are not appropriate for everyone.

Principal protectionfrom market-index losses
Income planningfor a retirement paycheck
Tax deferraluntil money is withdrawn
Personal reviewbased on your situation
A safer bucket

Protection alongside growth—not instead of everything else.

A well-designed retirement strategy may divide money by purpose. Investments can provide growth potential, while a protected bucket can help cover future income needs without being directly exposed to stock-market losses.

The goal is not to put every dollar into an annuity. It is to decide whether part of your retirement savings should have a different job.

The question to consider
“If the market dropped 20%, would your retirement income plan need to change?”

A review can help identify how much risk you are carrying and whether a protected-income strategy deserves consideration.

Understand the tools

Three common annuity strategies.

Different annuities solve different problems. Product details, surrender periods, liquidity, rates, caps, participation rates, fees, and income options must be reviewed carefully.

01

Fixed Indexed Annuity

Interest may be linked to the performance of a market index, subject to contract limits, without directly investing in the index. Contract value is protected from negative index performance.

  • Downside protection from index losses
  • Tax-deferred accumulation
  • Optional income features may be available
02

Multi-Year Guaranteed Annuity

A MYGA credits a declared fixed rate for a stated period. It may be considered when comparing predictable returns with CDs or other fixed-rate choices.

  • Known rate for the guarantee period
  • Tax-deferred interest
  • Surrender terms and access matter
03

Lifetime Income Strategy

Some annuities can create an income stream designed to continue for life. Income benefits and account value are different measurements and should be explained separately.

  • Predictable retirement income
  • Longevity-risk planning
  • Options for one or two lives
Start with the right questions

Five things to clarify before choosing an annuity.

1

When will you need income from this money?

2

How much liquidity must remain available?

3

How would a major market decline affect your plans?

4

Is growth, guaranteed income, or principal protection the priority?

5

What surrender period and contract restrictions can you reasonably accept?

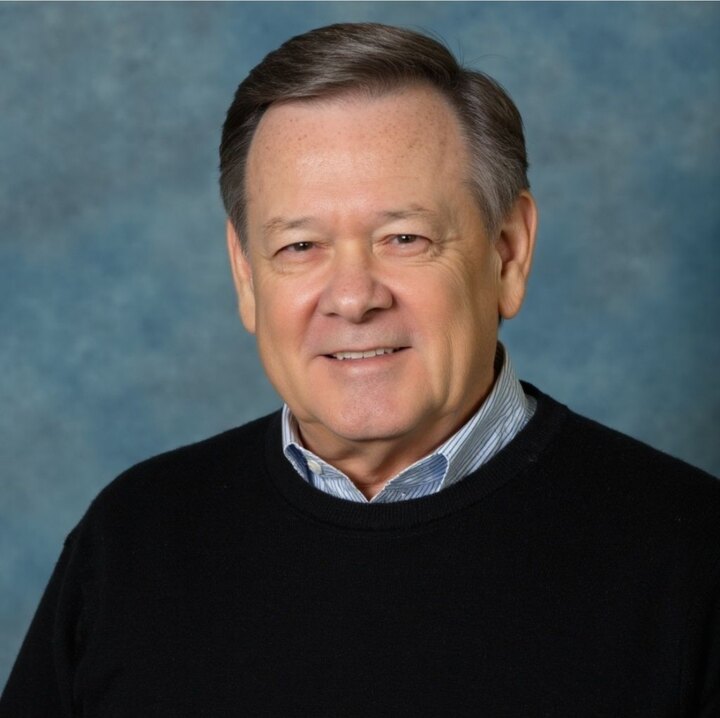
Michael Ryan, Financial Strategies Professional
About Mike

Plain-English guidance, grounded in service.

Michael Ryan is a licensed California insurance professional with Ryan & Associates, helping individuals and families evaluate retirement-protection and income strategies.

Mike’s approach is educational and needs-based: understand the full financial picture, explain the choices clearly, and determine whether an annuity fits alongside the rest of the plan.

Michael Ryan
Financial Strategies Professional
California Insurance License #0E99540

Your next step

Would more certainty improve your retirement plan?

Bring your current statements, income goals, and questions. We’ll work through the trade-offs together.

Schedule Your Review
Call MikeSchedule